Build with confidence,
from land to lock-up.
Construction finance has more moving parts than a standard loan. We structure it, manage every drawdown, and stay across the build with you, so the funding is there when the builder needs it.
We manage every drawdown stage, from slab to completion
Built for complex, self-employed and trust-based income
Structuring across multiple properties and projects
Based on 250+ reviews
The Adviser Elite Broker 2024 & 2025
We compare your rates with 50+ lenders


Why Stryve for your build
Construction Finance, Handled End To End
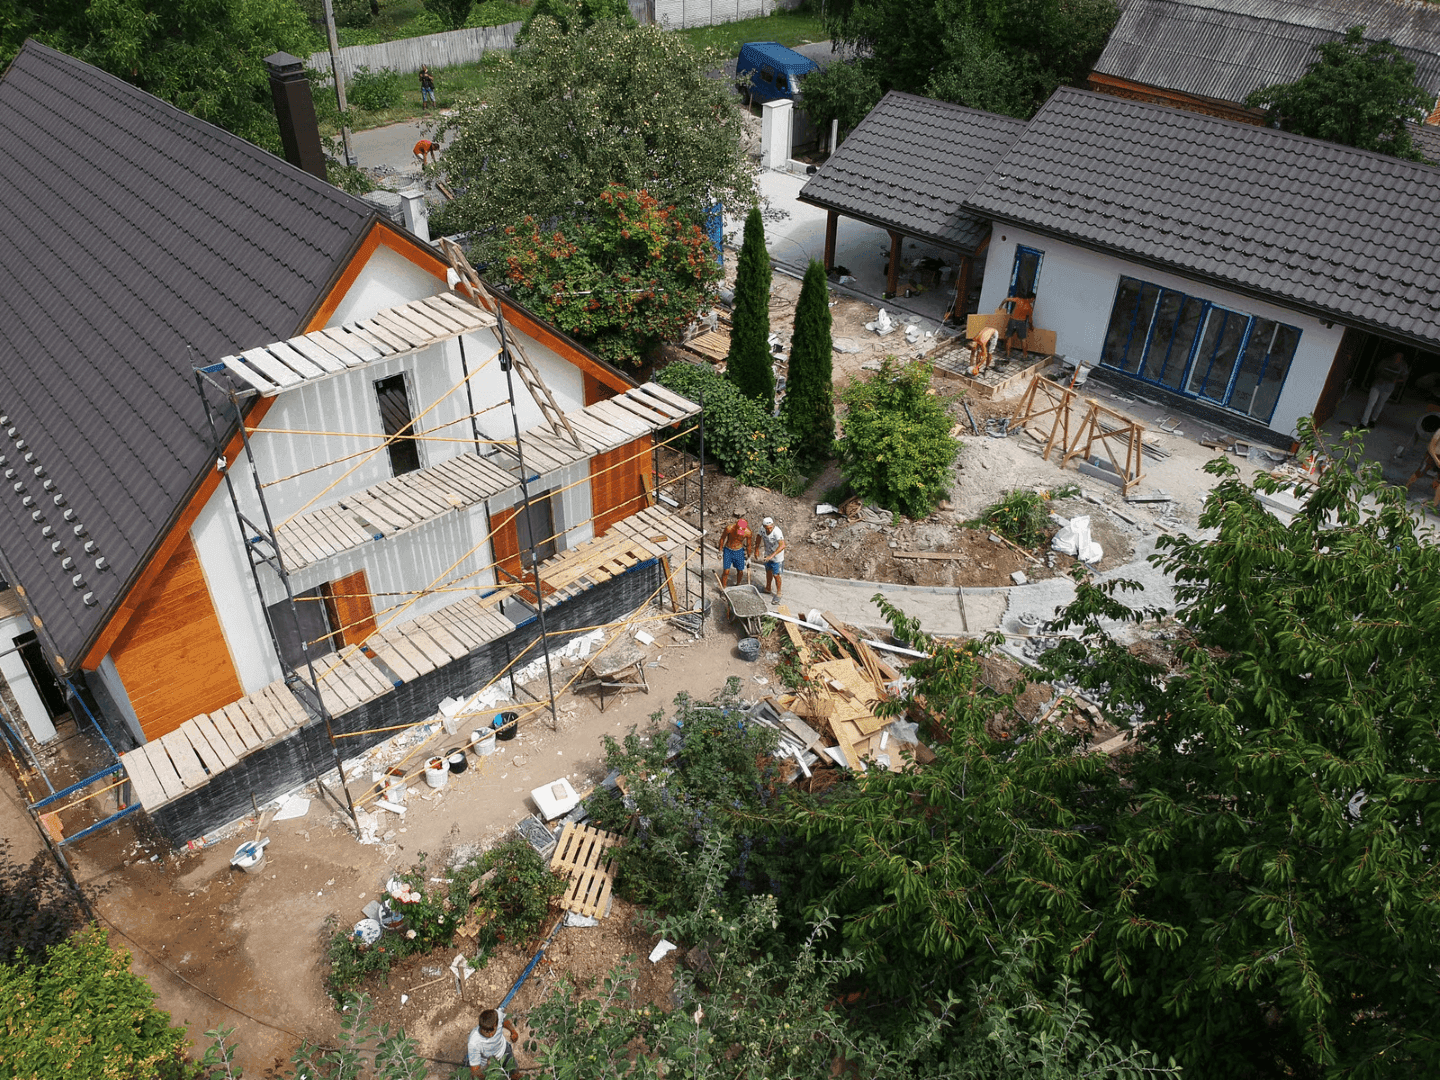
A construction loan isn't a single approval. It's a sequence of staged drawdowns released as your build hits each milestone, from slab to frame to lock-up to completion. Get the structure wrong and the consequences land at the worst time: a drawdown stalls, your builder isn't paid, and the whole project waits on the bank.
We set it up correctly from day one and manage every release for you, so funding keeps pace with the build instead of holding it up. Whether it's your first build or your fifth across a growing portfolio, you deal with one team that knows the file end to end.
Every stage managed
Each scheduled drawdown from slab to completion, not just the first approval.
Complex income, sorted
Self-employed, company and trust structures are our normal, not an exception.
Built around your portfolio
Structured across multiple properties and projects, not a single loan in isolation.
Our 5-Stage Construction Loan Process
A construction loan releases in stages as your build progresses, not all at once. Each release is tied to a milestone and signed off before funds flow. We've guided clients through builds of every size, and we manage each stage with the lender so you don't have to.
From land to keys, we're across every drawdown, so funding keeps pace with the build.
01
Structure
Before a brick is laid, we set the loan up correctly, confirming your borrowing position, land component, and total build cost so the funding is right from day one.
02
Land settlement
If you're buying the block, the first drawdown settles the land. We coordinate with the lender and your conveyancer so this step doesn't hold up the build start.
03
Progressive drawdowns
As construction hits each milestone (slab, frame, lock-up, fit-out) the lender releases the next payment. We manage each request and the valuations behind them, so your builder is paid on time at every stage.
04
Completion
At the final stage the last drawdown is released and the build is signed off. We make sure the final inspection and payment line up so there's no gap between finishing and moving in.
05
Settle into your loan
Once the build is complete, your loan typically converts to a standard mortgage. We review the structure with you and check it still fits, especially if it's one of several across your portfolio.
How construction finance works in your favour
You approve every drawdown
Funds release in stages tied to each build phase, and only once you've signed off on the inclusions and quality of work. You stay in control of what gets paid, when.
Interest only on what you've drawn
You pay interest only on funds released so far, not the full loan, and typically interest-only until completion. Your repayments grow with the build, not ahead of it.
Potential duty & grant savings
Building can attract lower stamp duty than buying established, plus first-build grants or concessions in some states. We'll confirm what applies to your situation.
Lender-vetted builders only
Because lenders require licensing and insurance before releasing funds, and payments only flow after each stage is verified complete, you're protected from unqualified work.
Why Business Owners Choose Stryve
Banks often put self-employed applicants in the "too hard" basket. We specialize in them.
Complex income, understood
Income held in trusts, retained earnings, or reinvested in the company. We know how to present your full picture to lenders.
Alternative documentation
No up-to-date tax returns? We work with lenders who accept BAS, business bank statements, or an accountant's letter.
Lenders beyond the banks
Direct access to private and non-bank commercial lenders with flexible terms you won't find on the high street.
Get expert advice for your build
Let's structure the right finance for your construction project.
Book a strategy callWhat our customers
say about us
“We had a great experience with Dylan and the team. Very professional and they took care of everything. We will definitely go through Stryve in the future.”

Carrissa Huisman
Google review, 27 Oct 2026
“Best in the business! Dylan and the team made getting my home loan simple and stress-free. They were attentive, responsive, and always kept me in the loop. Highly recommend!”

Zeki Ismen
Google review, 22 Oct 2026
“The team is awesome. Douglas and Dylan, are very thorough and are generous with their time to explore the best product that meets my needs and when they cover all the details, they follow through to the last details ensure the transaction is complete. They will also check after the issue is settled to see if any more support is needed. Simply A service. Best wishes and am sure where to go fir my next mortgage or financial advice.”

Emil
Google review, 13 Oct 2026
“Dylan and his staff have been fantastic, they have made the process very easy and stress free. They walk through everything with you from start to finish and guide you to the best options. Thank you guys much appreciated”

Paul Coleiro
Google review, 22 Sept 2026
“Dylan and the Stryve Team have been so amazing during our search for a first home. Dylan was so communicative, patient and knowledgable and kept us updated throughout the whole process. I can’t recommend them enough!”

Michael O'Malley
Google review, 30 Aug 2026
“My partner & I have had a fantastic experience with Stryve Finance. Dylan and Douglas were incredibly helpful, responsive and supportive throughout the entire process. We’re very grateful for their help and would highly recommend Stryve to anyone looking for a reliable and knowledgeable mortgage broker.”

Tanvi Mara
Google review, 19 Aug 2026
“Dylan and the team at Stryve are exceptional. He made the process so easy to understand and helped secure the loan I was after. A special mention to how efficient the team are and can move things really quickly when needed. Can’t thank them enough for everything they’ve done. Strongly recommend if you’re looking for a first class mortgage broker!”

JAMES HARVEY
Google review, 18 Aug 2026
Frequently asked questions
When you take out a construction loan, you’re effectively taking out two parts: one for the land, and one for the construction costs.
The lender will want evidence you have the funds to purchase the land, along with detailed plans and specifications for the project. They’ll also want your builder’s fixed-price quote so they can confirm the total cost of construction won’t exceed the loan, and funds are then released in stages as each phase of the build is completed.
